
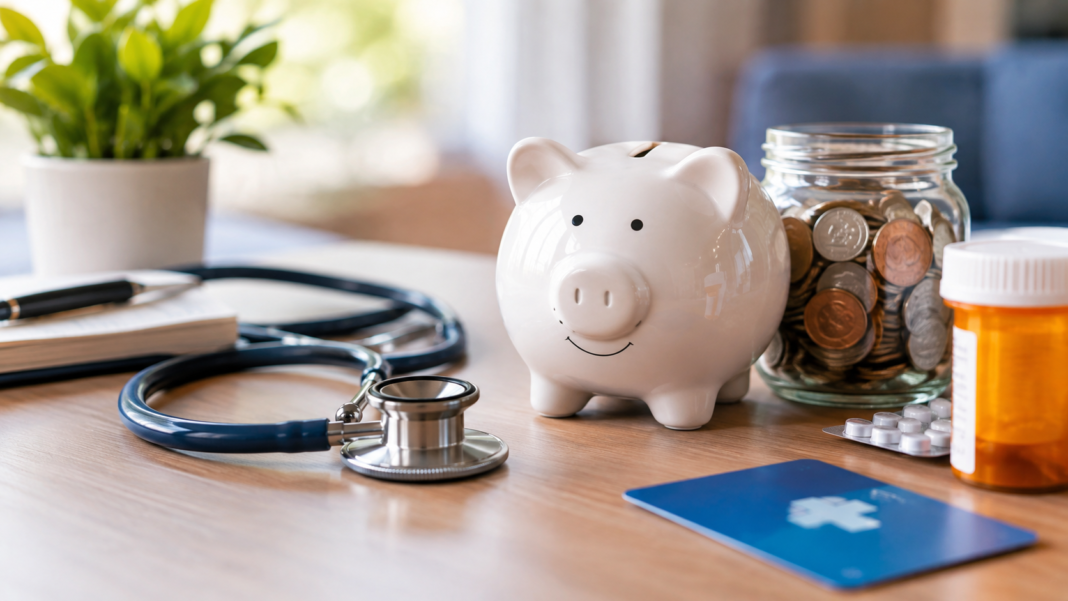
Everyday healthcare expenses can add up faster than expected. Copayments, prescriptions, dental visits, vision care, and other eligible expenses may become a regular part of a household budget. A health savings account can provide an additional financial tool for people who meet the applicable eligibility requirements.
An HSA is designed to help eligible individuals set aside money for qualified medical expenses. Contributions may receive favorable federal tax treatment, and withdrawals used for eligible expenses may receive tax advantages under applicable rules. Because regulations can change, account holders should review current requirements when planning their healthcare finances.
An HSA for America can help consumers learn more about health savings accounts and how they may fit into a healthcare planning strategy. However, individuals should always consider their own insurance coverage, finances, and eligibility before making decisions.
HSAs can be particularly useful when paired with a qualifying High Deductible Health Plan. The account can give an eligible person a dedicated place to save for healthcare costs instead of paying every unexpected expense directly from a regular checking account.
One advantage of planning ahead is that medical expenses are often easier to manage when money has already been set aside. A household can contribute to its account over time and use those funds when eligible healthcare expenses arise.
It is important to understand what expenses qualify. Not every purchase related to health or wellness necessarily qualifies for tax advantaged HSA treatment. Qualified expenses generally relate to medical care under applicable rules, while ordinary personal purchases may not qualify.
Keeping receipts and records is therefore a useful habit. Even when an HSA provider does not immediately request documentation, account holders should maintain records supporting withdrawals and eligible expenses.
An HSA can also provide flexibility when healthcare needs change. A person may have relatively low medical expenses in one year and higher costs in another. Building savings during lower expense periods can create a financial cushion for future healthcare needs.
Families should also consider whether their insurance plan is actually HSA eligible. Not every plan described as having a high deductible automatically qualifies. The plan must meet applicable federal requirements, and other circumstances can affect HSA eligibility.
Healthcare budgeting can become easier when insurance and HSA savings are considered together. A family might estimate annual premiums, expected medical expenses, and a reasonable amount to contribute to an HSA. This can provide a more complete picture than looking at insurance premiums alone.
HSAs can also be useful for planned healthcare expenses. If someone expects regular dental treatment, prescription costs, or other qualified medical expenses, saving in advance may reduce the financial pressure when those bills arrive.
Account holders should also understand the difference between an HSA and other healthcare accounts. Rules concerning contributions, withdrawals, eligibility, and tax treatment can differ, so it is important to know which type of account is being used.
Good record keeping remains essential. Keeping account statements, receipts, and explanations of benefits in an organized location can make it easier to understand how healthcare expenses were paid and support appropriate tax reporting.
An HSA is not a replacement for health insurance. Instead, it can complement qualifying coverage by providing a dedicated way to save for eligible healthcare expenses.
For eligible consumers, combining insurance planning with disciplined HSA savings can make everyday medical costs easier to anticipate. An HSA for America can be one resource for learning about these accounts and considering how they may fit into a broader healthcare budget.
 can help manage medical costs, save for eligible expenses, and plan your healthcare budget wisely.)